NRI Income Tax in India: Rules, ITR Filing & Taxable Income Explained (2026)

An NRI in Dubai sells an old flat in Gurgaon and watches the buyer deduct a massive chunk as TDS. Another in the US receives a notice for interest income he never knew was taxable in India. NRI income tax in India problems rarely come from evasion — they come from not knowing which income India taxes and which it does not.

This guide explains how NRI income tax works for AY 2026-27: how residential status is decided, what income is taxable in India, how NRE and NRO accounts differ, the TDS rules that bite hardest, DTAA relief, and the correct way to file your Indian return from abroad.

Who Is an NRI for Income Tax? Residential Status Rules

Your tax liability in India depends on residential status under Section 6, tested every financial year. You are a resident if you spend 182 days or more in India during the year, or 60 days or more in that year plus 365 days or more across the preceding four years. Fail both tests, and you are a non-resident (NRI) for that year.

Important carve-outs modify the 60-day rule: for an Indian citizen leaving for employment abroad or as a crew member, and for citizens/PIOs visiting India, the threshold extends to 182 days — though for visiting citizens/PIOs with India-sourced income above ₹15 lakh, the limit tightens to 120 days. High-income citizens not taxed in any other country can also be “deemed residents” in specific cases.

Count your days carefully every year, with passport stamps as evidence. Status drives everything that follows.

What Income Is Taxable in India for NRIs?

The principle is simple: NRIs are taxed in India only on income received or accruing in India. Global income stays outside the Indian net (unlike residents).

Income Type

Taxable for NRI in India?

Notes

Salary for services rendered in India

Yes

Taxed even if paid abroad

Rent from property in India

Yes

Tenant deducts TDS; standard deduction available

Capital gains on Indian assets

Yes

Property, shares, mutual funds — buyer/broker-level TDS applies

Interest on NRO account

Yes

TDS at 30% (plus cess) is common

Interest on NRE and FCNR deposits

No (exempt)

Exempt while you qualify as NRI under FEMA conditions

Foreign salary and foreign business income

No

Outside Indian tax net for NRIs

TDS Rules Every NRI Must Know

  • Property sale (Section 195): buyers must deduct TDS on payments to NRIs at rates linked to the capital gains tax — far higher than the 1% for residents. Apply to the assessing officer for a lower/nil deduction certificate before the sale to avoid locking up funds.
  • Rent: tenants paying rent to an NRI landlord must deduct TDS under Section 195 at the applicable rate.
  • NRO interest: banks deduct TDS at 30% plus cess by default; DTAA can lower this with the right paperwork.
  • Shares and mutual funds: capital gains TDS applies at prescribed rates when NRIs redeem or sell.

Because TDS often exceeds the actual final tax, filing an Indian ITR is frequently the only way an NRI recovers the excess as a refund.

DTAA: How NRIs Avoid Double Taxation

India has Double Taxation Avoidance Agreements with dozens of countries, including the UAE, USA, UK, Singapore and Australia. DTAA either taxes an income in one country only or allows credit in your home country for tax paid in India.

To claim treaty benefits, obtain a Tax Residency Certificate (TRC) from your country of residence and furnish Form 10F along with prescribed details. Without these documents, banks and payers apply full domestic TDS rates.

How NRIs Should File ITR in India: Step-by-Step

  1. Determine your residential status for the year. Count India days precisely; borderline years deserve professional confirmation.
  2. Check whether filing is required. File if Indian taxable income exceeds the basic exemption limit — or file voluntarily to claim TDS refunds and carry forward capital losses.
  3. Choose the correct form. NRIs generally file ITR-2 (or ITR-3 with business income in India); ITR-1 is not available to non-residents.
  4. Reconcile with Form 26AS and AIS. Every TDS entry and reported transaction should match your return.
  5. Report exempt income and apply DTAA correctly. Disclose NRE interest as exempt where applicable and claim treaty relief with TRC/Form 10F.
  6. Pre-validate an Indian bank account for refunds. An active NRO account works for refund credit.
  7. File and e-verify from anywhere. Aadhaar OTP, net banking or other e-verification completes the process fully online — no India visit needed.

Common NRI Income Tax Mistakes

  • Continuing to use a resident savings account after becoming an NRI instead of re-designating it as NRO — a FEMA compliance issue.
  • Assuming NRO interest is exempt like NRE interest and skipping the return.
  • Selling property without a lower-TDS certificate and waiting a year for a large refund.
  • Ignoring the 120-day rule after taking up substantial India-sourced income, and accidentally becoming a resident.
  • Missing DTAA paperwork (TRC/Form 10F) and paying avoidable higher TDS.
  • Not reporting Indian capital gains from mutual funds because ‘the money never left India’.

Smart Tax Planning Tips for NRIs

  • Keep deposits in NRE/FCNR while you qualify — the interest is tax-free in India.
  • Plan property sales: gain computation, lower-deduction certificate, and Section 54/54EC reinvestment options can transform the outcome.
  • Maintain a simple day-count tracker for India visits, especially in years of relocation.
  • Review status every year around March if you travel frequently — one extra fortnight in India can flip your status.
  • Use a professional for the transition years (leaving or returning to India); these are where the costliest mistakes occur.

Conclusion

NRI income tax follows one clean principle — India taxes what arises in India — surrounded by details that matter: day-count rules, NRE-versus-NRO treatment, steep Section 195 TDS, DTAA paperwork and the right ITR form. Master the details, and Indian compliance from abroad becomes a two-hour annual task with refunds arriving on time.

Ignore them, and TDS, notices and locked-up money follow you across borders.

Living abroad with income in India? KKS Capital Advisors specializes in NRI tax filing, lower-TDS certificates, DTAA relief and property sale planning — handled remotely, end to end. Schedule a virtual consultation with our NRI tax experts today.

This guide breaks down exactly who needs a tax audit for AY 2026-27, the current turnover limits with the digital-transaction relaxation, the forms involved, due dates, penalties for default, and how to prepare so the audit is a formality rather than a fire drill.

What Is a Tax Audit Under Section 44AB?

A tax audit under Section 44AB is a mandatory examination of a taxpayer’s books of account by a practising Chartered Accountant, required when business turnover or professional receipts cross specified limits. The CA verifies that books are properly maintained and reports prescribed particulars to the Income Tax Department in Form 3CA/3CB along with the detailed statement in Form 3CD.

Its purpose is simple: give the department assurance that income is computed correctly under the Income-tax Act, and flag disallowances, TDS defaults and reporting gaps in a standard format.

Tax Audit Applicability: Turnover Limits for AY 2026-27

Taxpayer Category

Threshold for Tax Audit

Key Condition

Business (general rule)

Turnover above ₹1 crore

Standard limit under Section 44AB(a)

Business (digital-heavy)

Turnover above ₹10 crore

Cash receipts AND cash payments each ≤ 5% of totals

Profession

Gross receipts above ₹50 lakh

Doctors, lawyers, architects, consultants and other specified professionals

Presumptive business (44AD) opt-out

Audit required despite lower turnover

Declaring profit below the presumptive rate while income exceeds the basic exemption limit

Presumptive profession (44ADA) opt-out

Audit required despite lower receipts

Declaring profit below 50% of receipts while income exceeds the exemption limit

The ₹10 crore relaxation is a genuine reward for going digital: if your cash receipts and cash payments are each within 5% of the respective totals, no audit is needed until ₹10 crore turnover. Keep banking trails clean and this benefit is yours.

Forms 3CA, 3CB and 3CD: What Gets Filed

  • Form 3CA: used when your accounts are already audited under another law — for example, a company audited under the Companies Act.
  • Form 3CB: used when there is no other statutory audit — typical for proprietorships, partnerships and professionals.
  • Form 3CD: the heart of the tax audit — a detailed statement of particulars covering depreciation, disallowances under 40(a)/40A/43B, TDS compliance, loans and deposits, GST turnover reconciliation and much more.

The auditor uploads these electronically, and you approve them through your e-filing account. Only then is the tax audit complete.

Tax Audit Due Date and Penalty for Default

For AY 2026-27, the tax audit report is ordinarily due by 30 September 2026, and the ITR for audited cases by 31 October 2026 (transfer-pricing cases get later dates). Watch for official extensions, but never plan around them.

Missing the audit invites a penalty under Section 271B: 0.5% of turnover or gross receipts, capped at ₹1,50,000. The penalty can be waived for reasonable cause, but prevention is infinitely cheaper than pleading.

How to Prepare for a Tax Audit: Step-by-Step

  1. Close and reconcile your books early. Bank reconciliations, debtor/creditor confirmations and stock records should be ready by the first quarter after year-end.
  2. Reconcile turnover with GST returns. Differences between books, GSTR-1 and GSTR-3B are the first thing every auditor — and the department — checks.
  3. Compile TDS compliance. Match expense-wise TDS deducted, deposited and returns filed; defaults trigger disallowances under 40(a)(ia).
  4. Organize loan and cash-transaction records. Sections 269SS/269ST compliance on cash loans and receipts is a standard 3CD reporting point.
  5. Fix the fixed asset register. Additions, deletions and depreciation as per Income-tax rules must be documentable.
  6. Engage your CA well before the deadline. August engagement beats September panic — quality of audit and of tax positions both improve.
  7. Review the draft 3CD before approval. Every clause you approve becomes departmental record; read it, question it, then accept it.

Tax Audit vs Statutory Audit: Don’t Confuse the Two

A statutory audit under the Companies Act applies to every company regardless of size, and examines whether financial statements show a true and fair view for shareholders. A tax audit under Section 44AB applies based on turnover or receipts thresholds — to companies, firms, proprietors and professionals alike — and reports income-tax-specific particulars to the department.

A private limited company crossing the 44AB threshold therefore undergoes both audits: the statutory audit first, and the tax audit reported in Form 3CA-3CD relying on those audited accounts. A proprietorship crossing the threshold undergoes only the tax audit, in Form 3CB-3CD.

Knowing which audit you need — and sequencing them correctly — avoids duplicated work and missed deadlines.

Common Mistakes Businesses Make Around Tax Audits

  • Measuring only turnover and ignoring the cash-percentage test that decides between the ₹1 crore and ₹10 crore limits.
  • Opting out of presumptive taxation with low declared profits and not realizing an audit has become mandatory.
  • Treating F&O trading casually — derivatives turnover is business turnover and can trigger audit obligations.
  • Leaving GST-vs-books turnover mismatches unexplained, gifting the department an easy notice.
  • Approving Form 3CD without reading it, then being surprised by what was reported.
  • Starting the audit in the last week of September, forcing rushed positions that cost real tax.

Benefits of a Well-Run Tax Audit (Beyond Compliance)

  • Early error detection: TDS gaps and disallowance risks get fixed before they become demands.
  • Cleaner funding conversations: banks and investors trust audited numbers.
  • Notice resistance: a robust 3CD trail closes most scrutiny questions quickly.
  • Better systems: the discipline of audit-readiness upgrades your accounting hygiene all year.

Conclusion

Tax audit under Section 44AB is triggered by more than a single number: the ₹1 crore/₹10 crore business limits with the 5% cash test, the ₹50 lakh professional limit, and the presumptive opt-out traps under 44AD/44ADA. Know which gate applies to you, prepare books early, reconcile with GST, and file Forms 3CA/3CB-3CD before 30 September.

Handled early, a tax audit is a routine health check. Handled late, it is a penalty magnet.

Crossed the audit threshold or unsure if you have? KKS Capital Advisors conducts end-to-end tax audits—book reviews, 3CD preparation, and filing—for businesses and professionals in Gurgaon. Book your audit consultation before the September rush.

FAQ'S

Q. Do NRIs have to pay tax in India?

Yes, but only on income received or accruing in India — such as rent from Indian property, capital gains on Indian assets, NRO interest and salary for services rendered in India. Foreign salary and overseas business income of an NRI are not taxed in India.

No. Interest on NRE and FCNR deposits is exempt from Indian income tax as long as you qualify as a non-resident under the applicable exchange-control conditions. Interest on NRO accounts, by contrast, is fully taxable and typically suffers 30% TDS plus cess.

NRIs generally file ITR-2. If the NRI has business or professional income in India, ITR-3 applies. ITR-1 (Sahaj) is not available to non-residents, even for simple salary or one-house-property situations.

Apply to the jurisdictional assessing officer for a lower or nil deduction certificate under Section 197 before the sale, based on the actual capital gains computation. With the certificate, the buyer deducts TDS at the approved lower rate instead of the steep default rates under Section 195.

You need a Tax Residency Certificate (TRC) from your country of residence for the relevant year, along with Form 10F and any self-declarations the payer requires. Without these, banks and other payers apply full domestic TDS rates instead of the treaty rate.
Read More

Tax Audit Under Section 44AB: Applicability, Turnover Limits & Due Dates (AY 2026-27)

Tax Audit Under Section 44AB: Applicability, Turnover Limits & Due Dates (AY 2026-27)

“My turnover crossed one crore — do I need a tax audit?” Every September, this question floods CA offices, usually days before the deadline. The answer depends on more than turnover: cash percentages, presumptive schemes, and declared profit rates all decide whether a tax audit under Section 44AB applies to you.

This guide breaks down exactly who needs a tax audit for AY 2026-27, the current turnover limits with the digital-transaction relaxation, the forms involved, due dates, penalties for default, and how to prepare so the audit is a formality rather than a fire drill.

What Is a Tax Audit Under Section 44AB?

A tax audit under Section 44AB is a mandatory examination of a taxpayer’s books of account by a practising Chartered Accountant, required when business turnover or professional receipts cross specified limits. The CA verifies that books are properly maintained and reports prescribed particulars to the Income Tax Department in Form 3CA/3CB along with the detailed statement in Form 3CD.

Its purpose is simple: give the department assurance that income is computed correctly under the Income-tax Act, and flag disallowances, TDS defaults and reporting gaps in a standard format.

Tax Audit Applicability: Turnover Limits for AY 2026-27

Taxpayer Category

Threshold for Tax Audit

Key Condition

Business (general rule)

Turnover above ₹1 crore

Standard limit under Section 44AB(a)

Business (digital-heavy)

Turnover above ₹10 crore

Cash receipts AND cash payments each ≤ 5% of totals

Profession

Gross receipts above ₹50 lakh

Doctors, lawyers, architects, consultants and other specified professionals

Presumptive business (44AD) opt-out

Audit required despite lower turnover

Declaring profit below the presumptive rate while income exceeds the basic exemption limit

Presumptive profession (44ADA) opt-out

Audit required despite lower receipts

Declaring profit below 50% of receipts while income exceeds the exemption limit

The ₹10 crore relaxation is a genuine reward for going digital: if your cash receipts and cash payments are each within 5% of the respective totals, no audit is needed until ₹10 crore turnover. Keep banking trails clean and this benefit is yours.

Forms 3CA, 3CB and 3CD: What Gets Filed

  • Form 3CA: used when your accounts are already audited under another law — for example, a company audited under the Companies Act.
  • Form 3CB: used when there is no other statutory audit — typical for proprietorships, partnerships and professionals.
  • Form 3CD: the heart of the tax audit — a detailed statement of particulars covering depreciation, disallowances under 40(a)/40A/43B, TDS compliance, loans and deposits, GST turnover reconciliation and much more.

The auditor uploads these electronically, and you approve them through your e-filing account. Only then is the tax audit complete.

Tax Audit Due Date and Penalty for Default

For AY 2026-27, the tax audit report is ordinarily due by 30 September 2026, and the ITR for audited cases by 31 October 2026 (transfer-pricing cases get later dates). Watch for official extensions, but never plan around them.

Missing the audit invites a penalty under Section 271B: 0.5% of turnover or gross receipts, capped at ₹1,50,000. The penalty can be waived for reasonable cause, but prevention is infinitely cheaper than pleading.

How to Prepare for a Tax Audit: Step-by-Step

  1. Close and reconcile your books early. Bank reconciliations, debtor/creditor confirmations and stock records should be ready by the first quarter after year-end.
  2. Reconcile turnover with GST returns. Differences between books, GSTR-1 and GSTR-3B are the first thing every auditor — and the department — checks.
  3. Compile TDS compliance. Match expense-wise TDS deducted, deposited and returns filed; defaults trigger disallowances under 40(a)(ia).
  4. Organize loan and cash-transaction records. Sections 269SS/269ST compliance on cash loans and receipts is a standard 3CD reporting point.
  5. Fix the fixed asset register. Additions, deletions and depreciation as per Income-tax rules must be documentable.
  6. Engage your CA well before the deadline. August engagement beats September panic — quality of audit and of tax positions both improve.
  7. Review the draft 3CD before approval. Every clause you approve becomes departmental record; read it, question it, then accept it.

Tax Audit vs Statutory Audit: Don’t Confuse the Two

A statutory audit under the Companies Act applies to every company regardless of size, and examines whether financial statements show a true and fair view for shareholders. A tax audit under Section 44AB applies based on turnover or receipts thresholds — to companies, firms, proprietors and professionals alike — and reports income-tax-specific particulars to the department.

A private limited company crossing the 44AB threshold therefore undergoes both audits: the statutory audit first, and the tax audit reported in Form 3CA-3CD relying on those audited accounts. A proprietorship crossing the threshold undergoes only the tax audit, in Form 3CB-3CD.

Knowing which audit you need — and sequencing them correctly — avoids duplicated work and missed deadlines.

Common Mistakes Businesses Make Around Tax Audits

  • Measuring only turnover and ignoring the cash-percentage test that decides between the ₹1 crore and ₹10 crore limits.
  • Opting out of presumptive taxation with low declared profits and not realizing an audit has become mandatory.
  • Treating F&O trading casually — derivatives turnover is business turnover and can trigger audit obligations.
  • Leaving GST-vs-books turnover mismatches unexplained, gifting the department an easy notice.
  • Approving Form 3CD without reading it, then being surprised by what was reported.
  • Starting the audit in the last week of September, forcing rushed positions that cost real tax.

Benefits of a Well-Run Tax Audit (Beyond Compliance)

  • Early error detection: TDS gaps and disallowance risks get fixed before they become demands.
  • Cleaner funding conversations: banks and investors trust audited numbers.
  • Notice resistance: a robust 3CD trail closes most scrutiny questions quickly.
  • Better systems: the discipline of audit-readiness upgrades your accounting hygiene all year.

Conclusion

Tax audit under Section 44AB is triggered by more than a single number: the ₹1 crore/₹10 crore business limits with the 5% cash test, the ₹50 lakh professional limit, and the presumptive opt-out traps under 44AD/44ADA. Know which gate applies to you, prepare books early, reconcile with GST, and file Forms 3CA/3CB-3CD before 30 September.

Handled early, a tax audit is a routine health check. Handled late, it is a penalty magnet.

Crossed the audit threshold or unsure if you have? KKS Capital Advisors conducts end-to-end tax audits — books review, 3CD preparation and filing — for businesses and professionals in Gurgaon. Book your audit consultation before the September rush.

FAQ'S

Q. What is the tax audit limit for AY 2026-27?

For businesses, audit applies above ₹1 crore turnover — extended to ₹10 crore when cash receipts and cash payments are each within 5% of totals. For professionals, the limit is gross receipts above ₹50 lakh. Presumptive opt-out cases can require audit even below these limits.

The tax audit report is ordinarily due by 30 September 2026, and the income tax return for audited cases by 31 October 2026, unless officially extended. Transfer-pricing cases have later statutory dates. Plan for the standard dates rather than hoping for extensions.

Section 271B prescribes a penalty of 0.5% of turnover or gross receipts, subject to a maximum of ₹1,50,000. The penalty may be dropped if you demonstrate reasonable cause for the failure, but avoiding default altogether is far safer and cheaper.

F&O trading is treated as business income, so the business audit limits apply to its turnover, computed per prescribed methods. Many active traders also fall into audit through the presumptive opt-out route when declaring profits below 6%/8% with income above the exemption limit.

Form 3CA is used when the taxpayer’s accounts are already audited under another law, such as a company under the Companies Act. Form 3CB applies when there is no other statutory audit — typical for proprietorships and firms. Both are accompanied by the detailed Form 3CD.

Read More

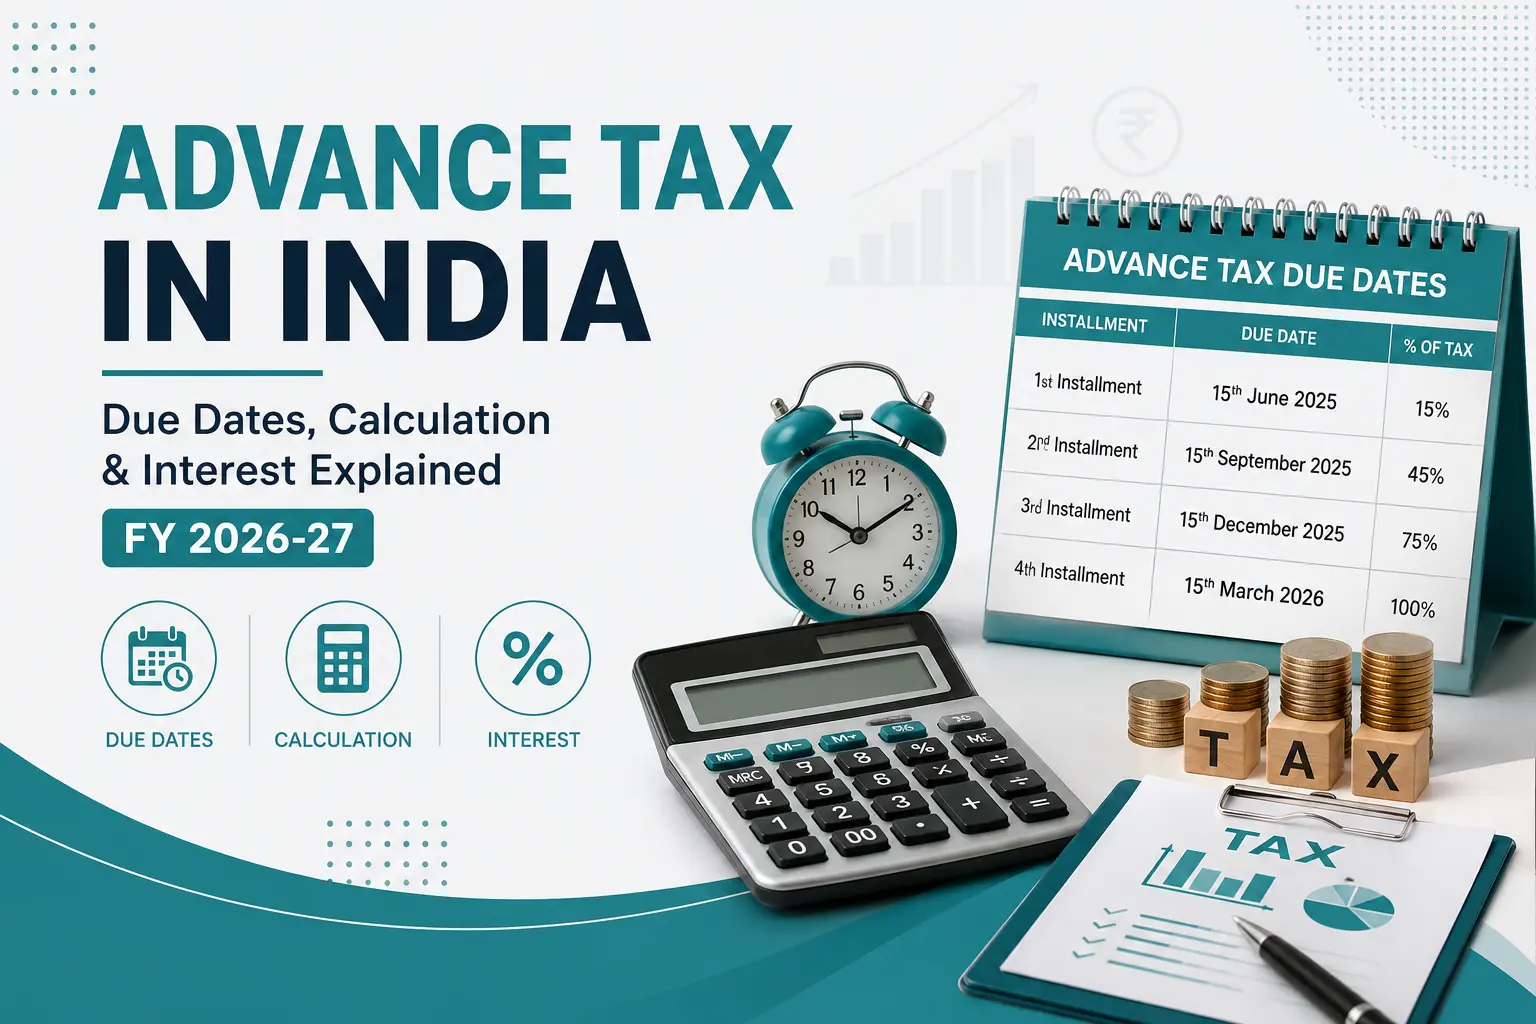
Advance Tax in India: Due Dates, Calculation & Interest Explained (FY 2026-27)

Advance Tax in India: Due Dates, Calculation & Interest Explained (FY 2026-27)

Freelancers, consultants, traders, and business owners often get their first shock at ITR time: the tax is paid, but the department still charges thousands in interest. The culprit is almost always missed advance tax — the pay-as-you-earn system most people discover only after the penalty-like interest hits.

This guide explains who must pay advance tax in India, the exact due dates and percentages for FY 2026-27, how to calculate each instalment, the interest under Sections 234B and 234C, and simple habits that keep you permanently interest-free.

What Is Advance Tax and Who Must Pay It?

Advance tax is income tax paid in instalments during the financial year itself, instead of one lump sum at return-filing time. It applies to every taxpayer — salaried, self-employed, or corporate — whose estimated tax liability for the year, after TDS, is ₹10,000 or more.

Salaried employees usually escape it because employer TDS covers their liability. The obligation typically bites people with income beyond salary: freelance or professional fees, business profits, capital gains, interest, dividends and rent.

One useful relief: resident senior citizens (60+) with no business or professional income are exempt from advance tax altogether.

Advance Tax Due Dates for FY 2026-27

Due Date

Cumulative Advance Tax Payable

Applies To

15 June 2026

15% of total estimated tax

All liable taxpayers

15 September 2026

45% of total estimated tax

All liable taxpayers

15 December 2026

75% of total estimated tax

All liable taxpayers

15 March 2027

100% of total estimated tax

All liable taxpayers

15 March 2027

100% in a single instalment

Presumptive taxpayers under 44AD / 44ADA

Note the special rule: businesses and professionals under the presumptive schemes (Sections 44AD and 44ADA) can skip the quarterly grind and pay the entire advance tax in one shot by 15 March.

How to Calculate Advance Tax: Step-by-Step

  1. Estimate your total income for the year. Include salary, business or professional income, capital gains, interest, dividends and rent.
  2. Apply deductions and pick your regime. Compute taxable income under the regime (old or new) you actually plan to use.
  3. Compute total tax including cess. Apply the slab rates plus 4% health and education cess, and surcharge if applicable.
  4. Subtract TDS and TCS. Reduce the tax already being deducted at source during the year.
  5. Check the ₹10,000 threshold. If the balance is ₹10,000 or more, advance tax applies.
  6. Pay as per the instalment schedule. Use the e-Pay Tax facility on the income tax portal; select the correct assessment year and challan (advance tax).
  7. Revise estimates every quarter. Income changes — a big project, a property sale, a market gain. Re-estimate before each due date and adjust the next instalment.

Interest for Missing Advance Tax: Sections 234B and 234C

Two separate interest charges apply, and they stack:

  • Section 234C — deferment interest: 1% per month for shortfalls in individual instalments, calculated against the 15/45/75/100 milestones (with limited tolerance margins for the first two instalments).
  • Section 234B — overall shortfall interest: if you pay less than 90% of your final tax by 31 March, 1% per month runs from 1 April until you clear the balance.

A helpful nuance: for instalment shortfalls caused purely by hard-to-predict income like capital gains or lottery winnings, 234C interest is spared if you pay the tax in the instalments falling due after the income arises.

A Quick Worked Example

Meera is a freelance designer in Gurgaon expecting ₹18 lakh of professional receipts in FY 2026-27. Opting for presumptive taxation under Section 44ADA, she offers 50% — ₹9 lakh — as income. Under the new regime, her estimated tax works out to roughly ₹40,000 after the applicable rebate structure and cess.

Since she is a 44ADA taxpayer, she can pay the entire estimated amount in a single instalment by 15 March 2027 — no June, September or December deadlines to track. If a large project doubles her receipts mid-year, she simply recomputes in February and pays the revised figure by 15 March.

Had Meera been a regular (non-presumptive) professional, the same tax would be split as ₹6,000 by June, ₹18,000 by September, ₹30,000 by December and ₹40,000 by March, on a cumulative basis.

Why Paying Advance Tax on Time Is Worth It

  • Zero interest drag: every skipped instalment converts into a silent 12% annualized cost.
  • Smoother cash flow: four smaller payments hurt far less than one giant March or July outflow.
  • Cleaner compliance profile: consistent advance tax history supports loan applications and reduces scrutiny triggers.
  • No refund lock-in: accurate estimates mean your money is neither stuck with the department nor short at year-end.

Common Advance Tax Mistakes to Avoid

  • Assuming salary TDS covers everything while side income from consulting, interest or trading quietly builds a liability.
  • Ignoring capital gains during the year and getting hit at the March instalment.
  • Estimating once in June and never revising, even after income doubles.
  • Paying under the wrong assessment year or challan head, then struggling to get credit.
  • Presumptive taxpayers forgetting the single 15 March deadline and walking into 234C.
  • Waiting for 31 March evening payments that fail due to bank cutoffs — pay a few days early.

Practical Tips to Stay Ahead of Advance Tax

  • Set calendar alerts one week before each due date: 15 June, 15 September, 15 December, 15 March.
  • Keep a simple running income tracker; fifteen minutes per quarter is enough for a solid estimate.
  • Move roughly 20–30% of every freelance or business receipt into a separate “tax” bank account.
  • After any windfall — property sale, bonus, big market gain — recompute immediately and pay in the next instalment.
  • If your income pattern is complex, have a CA prepare quarterly estimates; the fee is trivial against 234B/234C interest.

Conclusion

Advance tax is not an extra tax — it is the same tax, paid on time. The system is simple: estimate, pay 15/45/75/100 percent by the four due dates, revise every quarter, and Sections 234B and 234C never touch you.

The taxpayers who suffer are the ones who ignore it until July. A one-page quarterly estimate is all it takes to stay permanently interest-free.

Want your advance tax estimated and managed professionally? KKS Capital Advisors prepares quarterly tax estimates and handles payments for professionals, traders and businesses. Talk to our tax experts in Gurgaon today.

FAQ'S

Q. Who is required to pay advance tax in India?

Any taxpayer whose estimated tax liability for the year, after TDS, is ₹10,000 or more must pay advance tax — including freelancers, professionals, businesses and salaried individuals with significant non-salary income. Resident senior citizens without business income are exempt.

The instalments are 15% by 15 June 2026, 45% by 15 September 2026, 75% by 15 December 2026 and 100% by 15 March 2027 (cumulative). Presumptive taxpayers under Sections 44AD and 44ADA can pay the entire amount in one instalment by 15 March 2027.

Interest applies under Section 234C at 1% per month for the shortfall in that instalment, and under Section 234B at 1% per month from April if total payments fall below 90% of the final tax. The interest is automatic and added when you file your return.

Usually not, because employer TDS covers salary tax. But if you earn additional income — freelance fees, large interest, dividends, rent or capital gains — and the balance tax after TDS is ₹10,000 or more, advance tax applies on that portion.

Use the e-Pay Tax facility on incometax.gov.in: log in or enter PAN, select the correct assessment year, choose ‘Advance Tax’ as the payment type, and pay via net banking, UPI or debit card. Save the challan; it auto-reflects in your Form 26AS/AIS.

Read More

Input Tax Credit Under GST: Rules, Conditions & How to Claim ITC Correctly (2026)

Input Tax Credit Under GST: Rules, Conditions & How to Claim ITC Correctly (2026)

For most businesses, the single biggest hidden leak in GST is not the tax they pay — it is the credit they fail to claim. Input tax credit under GST can offset a huge share of your output tax, yet mismatched invoices, careless vendors and missed deadlines quietly destroy that benefit every month.

This guide explains what input tax credit (ITC) is, the exact conditions under Section 16, how GSTR-2B matching works, which credits are permanently blocked, and a practical monthly process to claim every rupee you are entitled to.

What Is Input Tax Credit Under GST?

Input tax credit under GST is the mechanism that lets a registered business reduce its output tax liability by the GST already paid on purchases of goods and services used for business. In simple terms: you collect GST on sales, subtract the GST you paid on eligible purchases, and deposit only the difference with the government.

This credit chain is the heart of GST. It removes the cascading “tax on tax” of the old regime — but only for businesses whose compliance is clean enough to keep the chain unbroken.

Conditions to Claim ITC: The Section 16 Checklist

You can claim input tax credit only when all of these conditions are satisfied:

  • Valid tax invoice or debit note: issued by a registered supplier with your correct GSTIN.
  • Receipt of goods or services: credit arrives only when you actually receive the supply (for goods in lots, on the last lot).
  • Invoice appears in your GSTR-2B: the supplier must have reported the invoice in their GSTR-1; unreported invoices give you no credit.
  • Tax actually paid by the supplier: the supplier must deposit the tax with the government.
  • You have filed your return: ITC is claimed through your GSTR-3B.
  • Payment to supplier within 180 days: fail to pay the supplier within 180 days of the invoice and the credit must be reversed with interest until you pay.

There is also a hard deadline: ITC for a financial year must be claimed by 30 November of the following year or the date of filing the annual return, whichever is earlier. Miss it, and the credit is gone forever.

How to Claim Input Tax Credit: Monthly Process

  1. Collect and verify purchase invoices. Check GSTIN, invoice number, tax amounts and your business name on every document.
  2. Download GSTR-2B after the 14th of each month. This auto-drafted statement lists the invoices your suppliers actually reported.
  3. Reconcile books vs GSTR-2B. Match every purchase entry; flag invoices missing from 2B and excess entries in 2B.
  4. Chase defaulting vendors immediately. Ask suppliers to report missed invoices in their next GSTR-1 — the earlier you chase, the higher the recovery.
  5. Claim eligible ITC in GSTR-3B. Claim only 2B-backed, eligible credit; park doubtful items until resolved.
  6. Reverse where required. Reverse credit for exempt-use, personal-use, 180-day payment failures and blocked categories.
  7. Document everything. Keep the reconciliation working — it is your first defence in any GST audit or notice.

Blocked Credits: Where ITC Is Not Allowed (Section 17(5))

Category

ITC Position

Key Exception

Motor vehicles for personal/staff use (seating ≤ 13)

Blocked

Allowed for resale, transport business, driving schools

Food, beverages, catering, club memberships

Blocked

Allowed if used to make the same category of outward supply, or where statutorily obligatory for employees

Works contract / construction of immovable property

Blocked

Allowed for plant & machinery and for further supply of works contract service

Goods lost, stolen, destroyed or given as free samples

Blocked

No general exception

Personal consumption purchases

Blocked

No exception


Claiming blocked credit is one of the fastest ways to attract a GST demand with interest and penalty. When a category looks grey, get a professional view before claiming.

Why Healthy ITC Management Directly Improves Profit

  • Cash flow: every rupee of matched credit is a rupee you do not pay in cash with GSTR-3B.
  • Pricing power: clean credit chains let you quote sharper prices than competitors leaking ITC.
  • Audit safety: reconciled ITC means fewer notices, faster closures and no panic at year-end.
  • Vendor discipline: monitoring 2B forces your supplier ecosystem to stay compliant.

ITC on Imports and Reverse Charge: Two Special Cases

Imports of goods carry IGST paid at customs, and that IGST is creditable like any other input tax — the bill of entry acts as your credit document, and the details flow into GSTR-2B from ICEGATE. Importers should reconcile customs data with 2B just as carefully as domestic purchases.

Under reverse charge (RCM), you pay the tax yourself on notified supplies — such as services from a goods transport agency or an advocate — and then claim credit of that very tax, provided the supply is used for business. The catch: RCM liability must be paid in cash, not by using existing credit, before the corresponding ITC becomes available.

Both cases reward good documentation. A missing bill of entry or an unrecorded RCM self-invoice is credit lost for no reason.

Common ITC Mistakes That Cost Businesses Money

  • Claiming credit from books instead of GSTR-2B, then facing mismatch notices.
  • Ignoring the 180-day supplier payment rule and skipping the required reversal.
  • Missing the 30 November cutoff for previous-year invoices during reconciliation.
  • Continuing to buy from vendors who habitually fail to file GSTR-1.
  • Claiming ITC on blocked categories like staff cars, canteen bills and office construction.
  • Not reversing proportionate credit when making both taxable and exempt supplies (Rule 42/43).

Best Practices to Maximize Input Tax Credit Under GST

  • Make monthly GSTR-2B reconciliation a fixed calendar ritual, not a year-end scramble.
  • Add a GST-compliance clause in vendor agreements — payment linked to invoice appearing in 2B.
  • Grade vendors by filing behaviour and shift volume toward compliant ones.
  • Automate matching with accounting software for volumes beyond a few hundred invoices.
  • Do a quarterly review of blocked-credit and reversal positions with your CA so year-end holds no surprises.

Conclusion

Input tax credit under GST rewards disciplined businesses and punishes casual ones. The rules are strict — Section 16 conditions, GSTR-2B matching, the 180-day payment rule, blocked categories and the 30 November deadline — but a simple monthly reconciliation routine converts all of that into real, recurring cash savings.

Treat ITC as a profit line, not a compliance chore, and it will behave like one.

Suspect ITC leakage in your business? KKS Capital Advisors runs complete ITC health checks, GSTR-2B reconciliations, and vendor compliance reviews for businesses in Gurgaon and across India. Book your GST consultation today.

FAQ'S

Q. What is the time limit to claim input tax credit under GST?

ITC for invoices of a financial year must be claimed by 30 November of the following financial year or the date of filing the annual return, whichever is earlier. Credit not claimed by this deadline lapses permanently, so year-end reconciliation is critical.

No. Credit is available only for invoices appearing in your GSTR-2B, which is generated from suppliers’ GSTR-1 filings. If a supplier fails to report your invoice, follow up and have them include it in a subsequent GSTR-1; until then, that credit cannot be claimed.

If you do not pay your supplier the invoice value plus tax within 180 days of the invoice date, the ITC claimed must be reversed along with interest. The credit can be re-claimed later once you actually make the payment to the supplier.

Section 17(5) blocks credit on items like motor vehicles for personal or employee use (with limited exceptions), food and catering, club memberships, construction of immovable property (other than plant and machinery), goods lost or given as free samples, and personal consumption purchases.

Yes, GST paid on capital goods used for business and taxable supplies is creditable in full when conditions of Section 16 are met. However, if you also claim income-tax depreciation on the GST component of the asset’s cost, ITC on that tax amount is not allowed.

Read More

Capital Gains Tax on Sale of Property in India: Rates, Exemptions & How to Save (2026)

Capital Gains Tax on Sale of Property in India: 2026 Guide

A property seller in Gurgaon recently discovered, after signing the sale deed, that nearly ₹30 lakh of his profit was headed straight to tax — money he could have legally saved with two weeks of planning. Stories like this repeat every day because most people learn about capital gains tax on sale of property only after the deal is done.

This guide explains how property sale gains are taxed in India in 2026, the current rates after the 2024 rule changes, every major exemption under Sections 54, 54F and 54EC, and the planning steps that protect your profit. Read it before you sell, not after.

What Is Capital Gains Tax on Sale of Property?

Capital gains tax on sale of property is the income tax charged on the profit you make when you sell land, a house, or any immovable property for more than its purchase cost. The gain is classified as short-term if you held the property for 24 months or less, and long-term if you held it for more than 24 months — and each is taxed differently.

Short-term capital gains (STCG) are added to your total income and taxed at your normal slab rate. Long-term capital gains (LTCG) enjoy concessional rates and, more importantly, powerful exemptions if you reinvest correctly.

Capital Gains Tax Rates on Property: What Applies in 2026

Budget 2024 changed the LTCG landscape for real estate. For property sold on or after 23 July 2024, the standard LTCG rate is 12.5% without indexation. However, resident individuals and HUFs selling property acquired before 23 July 2024 get a choice: pay 12.5% without indexation or 20% with indexation — whichever produces the lower tax.

Scenario

Holding Period

Tax Treatment

Short-term gain

Up to 24 months

Added to income; taxed at your slab rate

Long-term gain (general rule)

More than 24 months

12.5% without indexation

Long-term gain, property bought before 23 Jul 2024 (resident individual/HUF)

More than 24 months

Lower of 12.5% without indexation or 20% with indexation

Buyer-side TDS on purchase

Any (value ≥ ₹50 lakh)

Buyer deducts 1% TDS under Section 194-IA

This grandfathering choice is exactly where professional computation pays for itself. For old properties bought cheap, indexation at 20% often wins; for recent purchases, the flat 12.5% is usually better. Run both before you file.

How to Calculate Capital Gains on Property: Step-by-Step

  1. Start with the full sale consideration. Note that if the sale price is below the stamp duty (circle) value beyond the permitted tolerance, the stamp duty value can be treated as your sale price under Section 50C.
  2. Deduct transfer expenses. Brokerage, legal fees and other costs directly linked to the sale reduce your gain.
  3. Deduct the cost of acquisition. Your purchase price — indexed using the Cost Inflation Index if you choose the 20% indexation route for eligible property.
  4. Deduct the cost of improvement. Documented capital expenses like construction of a floor or major renovation (not routine repairs).
  5. Arrive at the capital gain. Classify it as short-term or long-term based on the 24-month holding rule.
  6. Apply exemptions before computing tax. Sections 54, 54F, 54EC and the Capital Gains Account Scheme can reduce the taxable gain — often to zero.

Capital Gains Exemptions: How to Legally Save Tax on Property Sale

Section 54 — Sell a house, buy a house

If you sell a residential house and reinvest the long-term gain in another residential house in India, the reinvested gain is exempt. Buy within one year before or two years after the sale, or construct within three years. If your gain is up to ₹2 crore, you can even invest in two houses — a once-in-a-lifetime option. Exemption is capped at ₹10 crore.

Section 54F — Sell any asset, buy a house

Selling a plot, commercial property or other long-term asset? Invest the net sale consideration in one residential house and claim proportionate exemption, subject to conditions like not owning more than one other house on the sale date.

Section 54EC — Invest in specified bonds

Invest up to ₹50 lakh of your gains in specified bonds (such as REC or NHAI/notified issuers) within six months of sale. The bonds carry a five-year lock-in, and the invested gain becomes exempt — a clean option when you do not want another property.

Capital Gains Account Scheme (CGAS)

Cannot finalize the new property before your ITR due date? Park the unutilized gain in a CGAS account with an authorized bank to preserve the exemption while you complete the purchase or construction within the allowed window.

Common Mistakes That Inflate Capital Gains Tax on Property

  • Ignoring Section 50C: selling below circle rate and getting taxed on a price you never received.
  • Missing the reinvestment deadlines under Section 54/54F, which cancels the exemption retroactively.
  • Forgetting improvement costs because bills were never preserved — keep every construction invoice.
  • Not comparing the 12.5% vs 20%-with-indexation options on pre-July 2024 property.
  • Overlooking the buyer’s 1% TDS under 194-IA while planning cash flows and refunds.
  • Splitting sale proceeds informally among family members without legal basis, inviting clubbing and scrutiny.

Smart Tips Before You Sell Property

  • Plan the sale date: crossing the 24-month holding mark can convert a slab-rate gain into a concessional long-term gain.
  • Get a tax computation done before signing the agreement, not at ITR time.
  • If reinvesting, match your exemption route (54, 54F, 54EC) to your actual life plans — do not buy a house you do not want just to save tax.
  • Report the transaction correctly in your ITR (Schedule CG); property deals are auto-reported to the department through registrars.
  • NRIs face different TDS rules on sale (deduction under Section 195 at higher rates) — plan for lower-deduction certificates in advance.

Conclusion

Capital gains tax on sale of property is one of the largest single tax events in most people’s lives — and also one of the most controllable. Know your holding period, compute the gain correctly, choose wisely between 12.5% and the indexation route where you have the option, and use Sections 54, 54F or 54EC before the deadlines lapse.

The difference between a planned sale and an unplanned one routinely runs into lakhs. Plan first, sign later.

Selling a property this year? Get a pre-sale capital gains computation and exemption plan from the chartered accountants at KKS Capital Advisors, Gurgaon. Book a consultation today and keep more of your profit — legally.

FAQ'S

Q. How much is capital gains tax on sale of property in India?

Long-term gains (property held over 24 months) are taxed at 12.5% without indexation; for property bought before 23 July 2024, resident individuals and HUFs can instead choose 20% with indexation if that is lower. Short-term gains are taxed at your normal slab rates.

Reinvest the long-term gain in another residential house under Section 54 (within the prescribed timelines), invest up to ₹50 lakh in Section 54EC bonds within six months, or use Section 54F when selling non-residential assets. Unutilized amounts can be parked in a Capital Gains Account Scheme before the ITR due date.

Yes. For resident sellers, the buyer deducts 1% TDS under Section 194-IA when the sale value is ₹50 lakh or more. For NRI sellers, the buyer deducts under Section 195 at much higher rates linked to capital gains tax, unless a lower-deduction certificate is obtained.

Immovable property qualifies as a long-term capital asset when held for more than 24 months from the date of acquisition. Selling at or before 24 months makes the gain short-term, taxed at slab rates without concessional treatment or major reinvestment exemptions.

Yes, the exemptions can be combined for the same sale. You may reinvest part of the gain in a residential house under Section 54 and up to ₹50 lakh in specified bonds under Section 54EC, reducing the taxable gain by both amounts, subject to each section’s conditions.

Read More

Section 194I of Income Tax Act, Everything You Need to Know in 2026

Section 194I of Income Tax Act, Everything You Need to Know in 2026

If you pay rent for an office, a shop, or machinery, this rule affects you directly. Section 194I of the Income Tax Act says that certain people must deduct tax before they pay rent. Miss it, and you could face interest, penalties, and disallowed expenses. The good news is that the rule is simple once you understand it.

This guide breaks down TDS under Section 194I in plain English. You will learn who must deduct, the current rates, the threshold limit, and a clear example. By the end, you will know exactly how to stay compliant.

What Is Section 194I of the Income Tax Act?

Section 194I of the Income Tax Act requires any person, except an individual or HUF not under tax audit, to deduct TDS on rent paid to a resident. TDS is deducted when the rent crosses the yearly threshold. The deducted tax is then deposited with the government on the landlord’s behalf.

In short, the rule brings rental income into the tax net. It helps the government track payments and reduces tax evasion. Tenants act as collecting agents and pass the tax to the department.

The provision applies to rent on land, buildings, machinery, plant, equipment, furniture, and fittings. So it covers far more than just a house or shop.

Who Must Deduct TDS Under Section 194I?

Not everyone has to deduct tax on rent. The rule targets businesses and larger taxpayers. Here is who falls under Section 194I TDS.

  •       Companies, firms, trusts, and societies paying rent to a resident
  •       Individuals and HUFs whose accounts need a tax audit under Section 44AB
  •       Local authorities, government bodies, and co-operative societies

Individuals and HUFs not under tax audit are not covered here. Instead, they may fall under Section 194IB, which is a separate provision for personal rent payments above ₹50,000 a month.

This split matters in real life. A salaried person renting a flat usually does not deal with Section 194I at all. But the moment a business pays rent above the limit, the rule kicks in. So your status decides which section applies to you.

TDS Rates Under Section 194I

The rate depends on what is being rented. Movable assets attract a lower rate than land and buildings. Here is the current rate chart for TDS on rent under Section 194I.

Rent type

TDS rate

Notes

Plant, machinery, equipment

2%

Lower rate for movable assets

Land or building

10%

Includes factory buildings

Furniture or fittings

10%

Applies when let out with property

No PAN given by landlord

20%

Higher rate under Section 206AA

Tip: No surcharge or cess is added to these rates for resident landlords. The plain rate applies.

Threshold Limit for TDS on Rent

You only deduct tax once rent crosses the limit. For FY 2025-26, the threshold under Section 194I is ₹50,000 per month, which works out to ₹6 lakh a year. This was raised from the earlier limit of ₹2.4 lakh a year.

If the rent stays below this limit, no TDS is needed. Once it crosses, you deduct tax on the full rent amount, not just the part above the limit. Always check the monthly figure carefully.

Keep one more thing in mind. The limit applies per landlord, per year. If you pay rent to two different owners, you check each one against the threshold on its own. The building and the furniture may even be owned by different people, and you treat each payment separately.

Section 194I of Income Tax Act With Example

Let us make this practical. Here is a simple example of how TDS under Section 194I works.

Example:

ABC Pvt Ltd rents an office from Mr. Sharma for ₹80,000 per month. The yearly rent is ₹9,60,000, which is above the ₹6 lakh threshold. So TDS applies.

Since this is a building, the rate is 10%. ABC Pvt Ltd deducts ₹8,000 each month (10% of ₹80,000). It pays Mr. Sharma ₹72,000 and deposits ₹8,000 with the government. Over the year, the company deducts ₹96,000 as TDS.

Mr. Sharma can claim credit for this ₹96,000 when he files his income tax return. So he is not taxed twice.

When and How to Deposit the TDS

Timing matters. You deduct TDS at the earlier of two events: when you credit the rent to the landlord’s account, or when you actually pay it.

  1.     Deduct TDS at the time of credit or payment, whichever is earlier.
  2.     Deposit the tax with the government by the 7th of the next month.
  3.     For rent credited in March, deposit by 30th April.
  4.     File the quarterly TDS return and issue Form 16A to the landlord.

Benefits of Following Section 194I

  •       You avoid interest and penalties for non-deduction
  •       You keep your rent expense deductible in your books
  •       Your landlord gets clean tax credit and fewer disputes
  •       You stay audit-ready and compliant all year

Common Mistakes to Avoid

Small errors in TDS can cost a lot. Watch out for these frequent slip-ups.

  •       Forgetting to collect the landlord’s PAN, which triggers 20% TDS
  •       Deducting only on the amount above the threshold instead of the full rent
  •       Mixing up Section 194I with Section 194IB for personal rent
  •       Missing the monthly deposit deadline and paying interest
  •       Deducting TDS on a refundable security deposit, which is not required

FAQ'S

Q1. What is the TDS rate under Section 194I?

TDS under Section 194I is 2% on rent for plant, machinery, and equipment, and 10% on rent for land, buildings, and furniture. If the landlord does not provide a PAN, the rate rises to 20%.

For FY 2025-26, TDS under Section 194I applies when rent exceeds ₹50,000 per month, or ₹6 lakh per year. Below this limit, no TDS is required. Once crossed, tax is deducted on the full rent.

Companies, firms, trusts, and individuals or HUFs under tax audit must deduct TDS on rent paid to residents. Individuals and HUFs not under tax audit are covered separately by Section 194IB.

No. If GST is shown separately in the invoice, TDS under Section 194I is deducted only on the rent, not on the GST. If rent and GST are not split, TDS applies to the full amount.

If you skip TDS under Section 194I, you may face interest, penalties, and disallowance of the rent expense. This raises your taxable income. It is best to deduct and deposit on time.

Conclusion: Stay Compliant With Section 194I

Section 194I of the Income Tax Act is easy to follow once you know the rate, the threshold, and the deadlines. Deduct at the right rate, collect the PAN, and deposit on time. That keeps you safe from interest and penalties.

Tax rules change often, so it helps to have an expert by your side. KKS Capital Advisors can manage your TDS, rent compliance, and filings end to end. Contact KKS Capital Advisors today for a quick consultation and stay worry-free.

Read More

Top 10 CA Firms in Gurgaon, Find the Right CA for Your Business

Top 10 CA Firms in Gurgaon: 2026 Expert Guide

INTRODUCTION

Picking the right chartered accountant can save you lakhs in taxes and hours of stress. If you run a business or earn a steady income, you already know how tricky compliance can get. That is exactly why this guide to the top 10 CA firms in Gurgaon exists. Gurgaon is a fast-growing corporate hub, and the demand for a reliable CA in Gurgaon has never been higher.

Below, you will find a clear comparison of the top CA firms in Gurgaon, what they do best, and how to choose the right one for your needs. Whether you are a founder, a salaried professional, or a growing SME, this list will help you decide with confidence.

Why Choosing the Right CA in Gurgaon Actually Matters

Gurgaon is not an ordinary city for business. It is home to more than 150 multinational offices inside DLF Cyber City alone. Thousands of PE-backed startups operate out of Golf Course Extension Road. Udyog Vihar houses hundreds of trading and manufacturing companies with active import-export compliance needs.

So when someone searches for the top 10 CA firms in Gurgaon, they are not just browsing. They have a real problem — GST notices, tax planning, an upcoming audit, or a company they need to register — and they need the right person to handle it.

The wrong CA can cost you far more than their fee.

A good chartered accountant in Gurgaon does not just file returns. They help you build clean financial systems, avoid compliance landmines, and make sure the numbers actually work for your business. And in a market as complex as Gurugram — where Haryana’s CGST Commissionerate, ROC filings, Section 44AB audits, and transfer pricing norms all apply — experience and local expertise genuinely matter.

This guide covers the top CA firms in Gurgaon for 2026, based on their service depth, local presence, client profile, and what they are actually best at. We have also included KKS Capital Advisors, a leading name among chartered accountant firms in Gurgaon for businesses that need both financial advisory and compliance under one roof.

Top 10 CA Firms in Gurgaon — Quick Comparison Table

#

Firm Name

Location

Best For

Specialisation

1

KKS Capital Advisors

Gurgaon

Startups, SMEs, Corporates

Tax, GST, Audit, Corporate Finance, Valuation

2

PwC India

DLF Cyber City, Phase II

Large corporates, MNCs

Tax, Deals, Transfer Pricing, Assurance

3

KPMG India

DLF Cyber City, Phase II

Listed companies, ESG

Audit, Advisory, Forensics, Risk

4

AKM Global

Sector 48, Sohna Road

MNCs, Expats

International Tax, FEMA, Transfer Pricing

5

Grant Thornton Bharat

DLF Cyber City

Mid-market, IPO-bound

Audit, Deals, ESG, Risk Consulting

6

ASA & Associates LLP

Sector 42, Golf Course Rd

India-entry, Foreign Cos

Audit, IFRS, Accounting Outsourcing

7

Nangia Andersen India

Sector 61, Golf Course Ext

NRIs, Family Offices, M&A

FEMA, International Tax, NRI Taxation

8

BDO India

Sector 58, Gurugram

Outsourcing, Risk Advisory

Audit, Tax, BPO, Digital Advisory

9

DSRV and Co LLP

Sector 48 & Cyber City

FEMA, 15CA/CB, NGOs

International Tax, GST Audit, FCRA

10

Deloitte (Haskins & Sells)

DLF Cyber City, Phase II

Large MNCs, M&A

Audit, Tax, Forensic, Risk Advisory

Detailed Profiles of Top CA Firms in Gurgaon

1. KKS Capital Advisors — Gurgaon

KKS Capital Advisors

KKS Capital Advisors is a full-service chartered accountancy and financial advisory firm based in Gurgaon. It serves startups, SMEs, and growing corporates that need more than just compliance — they need strategic financial guidance alongside it.

The firm handles tax advisory, GST registration and compliance, accounting and audit, corporate finance, business valuation, and business incubation support. For founders and promoters who are building something serious, KKS Capital Advisors offers a combination that most standalone CA firms do not: the technical depth of a chartered accountancy practice plus the strategic lens of a corporate finance advisor.

What makes KKS Capital Advisors particularly relevant among the gurgaon top ca firms is their focus on business-owners who are scaling. Whether it is structuring a fundraise, preparing for an audit, managing tax exposure, or valuing a business for a transaction, the firm brings all of it under one team. That matters when you are growing quickly and cannot afford to manage five different advisors for five different problems.

Best for: Startups raising capital, SMEs needing clean books and compliance, corporates seeking tax advisory, and businesses preparing for M&A or valuation.

Website Address: https://www.kkscapital.com/
Contact Number: +91 9654073033
Email: info@kkscapital.com
Business Address: 2nd Floor, SCO 12, Sector 23A, Gurgaon Near Bank of Maharashtra

2. PwC India — DLF Cyber City, Phase II

PwC’s Gurgaon office is one of the most active in its India network. The Deals practice here is particularly strong, given the density of PE/VC transactions originating from the Cyber City corridor.

Best for: Large listed companies, MNC subsidiaries needing statutory audit, businesses with cross-border structures and transfer pricing exposure.

Specialisations: Audit and assurance, direct tax, international tax, GST, deals/transaction advisory, transfer pricing, risk assurance.

3. KPMG India — DLF Cyber City, Phase II

KPMG’s Gurgaon presence is especially strong in Risk Consulting and ESG advisory — two areas that are growing faster than traditional audit in the corporate client base here. Their internal audit and SOX compliance practice is a market leader in the region.

Best for: Large companies needing risk consulting, ESG reporting, forensic investigations, and statutory audit for listed entities.

4. AKM Global — Sector 48, Sohna Road

AKM Global is Gurgaon’s most prominent home-grown large CA firm — headquartered here, not just maintaining a branch office. With 700+ professionals and 40+ years in practice, they are the first name most MNCs mention when they want Big-4-quality international tax work at a more competitive fee.

Best for: MNCs with India operations, expatriate-heavy companies, businesses with transfer pricing or cross-border M&A needs.

Specialisations: International tax, transfer pricing, expat/mobility tax, FEMA, outsourced accounting, M&A tax.

5. Grant Thornton Bharat — DLF Cyber City

Grant Thornton occupies a strong middle ground in the Gurgaon market — Big-4 credibility for mid-market clients who do not need Big-4 fees. Their Deal Advisory practice has been one of the most active in the NCR region, and their structured articleship programme (CampACE) is genuinely one of the best outside the Big 4.

Best for: Mid-market listed and unlisted companies, businesses planning fundraising, M&A, or IPOs, and companies with sustainability reporting requirements.

6. ASA & Associates LLP — Sector 42, Golf Course Road

ASA’s Baker Tilly International affiliation makes it the logical choice for foreign companies entering India, and for Indian companies with international counterparties. With 1,000+ professionals and a deep India-entry practice, they handle inbound FDI structuring, FEMA filings, and Ind AS advisory with genuine depth.

Best for: Foreign companies entering India, mid-market statutory audit, businesses needing Baker Tilly global network connectivity.

7. Nangia Andersen India — Sector 61, Golf Course Extension Road

Nangia Andersen is the only firm in Gurgaon with a genuinely deep family office and NRI wealth advisory practice alongside its corporate tax work. The Andersen Global membership (170+ countries) means the firm handles inbound and outbound cross-border transactions that smaller firms simply cannot.

Best for: NRIs with India assets or income, family offices, businesses with complex FEMA exposure, cross-border M&A.

Specialisations: FEMA and RBI compliance, NRI taxation, transfer pricing, international tax, M&A tax, ESG.

8. BDO India — Sector 58, Gurugram

BDO India’s Gurgaon office is particularly well-regarded for its Risk Advisory and Business Process Outsourcing practices. It is the 5th-largest professional services network globally, and for mid-market businesses wanting Big-4-standard audit at a more accessible price point, BDO is a natural fit.

Best for: Mid-market businesses needing outsourced accounting, risk advisory, and process consulting alongside conventional audit and tax.

9. DSRV and Co LLP — Sector 48 and Cyber City

DSRV is one of Gurgaon’s oldest boutique firms with nearly four decades of practice. Its particular strength in FEMA/RBI compliance and 15CA/CB certification makes it indispensable for businesses with outward remittances, foreign investments, or FCRA requirements.

Best for: Companies with FEMA exposure, outward remittance compliance, NGOs with FCRA obligations, and businesses needing GST audit.

10. Deloitte (Haskins & Sells) — DLF Cyber City, Phase II

Deloitte runs the largest article trainee intake in India and its Gurgaon presence covers the full suite — audit, tax, M&A advisory, forensic, and risk. For large corporations, Deloitte is often the default choice for statutory audit and management consulting.

Best for: Large MNCs, listed companies, businesses undergoing complex M&A or restructuring, and forensic investigations.

What Services Do CA Firms in Gurgaon Offer?

The services landscape in Gurgaon is broader than most Indian cities because the client base is disproportionately MNC-heavy, real estate-intensive, and startup-rich. Here is what the top CA firms in Gurgaon typically handle:

GST Compliance and Advisory This covers registration, monthly GSTR-1 and GSTR-3B filing, annual return (GSTR-9/9C), GST audit, input tax credit reconciliation, and advisory on complex transactions including e-commerce, real estate, and export of services.

Income Tax Return Filing Ranges from straightforward salaried ITRs to complex business returns involving multiple heads of income, capital gains, and foreign income disclosure (Schedule FA).

Statutory Audit and Tax Audit Statutory audit under the Companies Act 2013, and tax audit under Section 44AB, are non-negotiable for most medium and large businesses operating in Gurgaon.

Transfer Pricing This is uniquely important in Gurgaon because so many Cyber City and Udyog Vihar companies are subsidiary entities or shared-service centres of multinationals. Transfer pricing documentation and benchmarking is a specialized, high-stakes compliance area.

FEMA and RBI Compliance Covers FDI reporting (Form FC-GPR, FC-TRS), outward investment (ODI), 15CA/CB certificates, and FCRA for NGOs.

Business Valuation Required for FDI pricing compliance, ESOPs, M&A deals, and FEMA transactions. A firm like KKS Capital Advisors combines valuation with broader corporate finance advisory.

Virtual CFO Services Startups and SMEs use virtual CFO services to get outsourced financial management — MIS reporting, cash flow planning, investor relations support — without the cost of a full-time CFO.


Company Registration and ROC Compliance Includes incorporation of private limited companies, LLPs, and OPCs; annual filings with ROC Haryana; and director KYC.

NRI Taxation Covers India tax return filing for NRIs, DTAA benefit claims, FEMA compliance, and repatriation planning.

How to Choose the Right CA in Gurgaon

The right chartered accountant firm in Gurgaon depends entirely on your business type, size, and specific compliance pressure. Here is a straightforward way to think about it:

Step 1 — Define your primary need. Are you looking for ongoing monthly compliance (GST + TDS + bookkeeping)? A one-time service (ITR filing, company incorporation, audit)? Or strategic advisory (valuation, fundraise structuring, tax planning)?

Step 2 — Match the firm to your scale. A startup with a ₹50L turnover does not need a Big 4. A listed company preparing for a statutory audit does not want a sole practitioner. Be honest about what level of firm your situation actually needs.

Step 3 — Check partner accessibility. In large firms, your engagement is often managed by junior staff. In boutique and mid-size firms, you often get direct partner access. Neither is inherently better — but you should know what you are getting.

Step 4 — Verify ICAI registration. Always check the firm’s registration status on the ICAI website before engaging. This takes two minutes and prevents a lot of problems.

Step 5 — Ask for an engagement letter. Any professional CA firm will provide a written engagement letter that defines scope, fees, and timelines. If a CA hesitates to put things in writing, that is a red flag.

Quick matching guide:

  • Startup (seed to Series A): KKS Capital Advisors for tax, valuation, and corporate finance; boutique firms for lean GST and ROC compliance.
  • MSME or proprietorship: Local firms with Gurgaon-specific knowledge for affordable bundled compliance.
  • MNC subsidiary or shared-service centre: AKM Global, Nangia Andersen, or the Big 4 for transfer pricing and group reporting.
  • NRI or HNI with India investments: Nangia Andersen India or DSRV for FEMA/NRI-specific work.
  • Business needing corporate finance + compliance: KKS Capital Advisors covers both under one roof.

Common Mistakes People Make When Hiring a CA in Gurgaon

People make the same mistakes, repeatedly. And they usually only find out something went wrong at the worst possible time — during a GST notice, an income tax scrutiny, or an investor due diligence.

Choosing on price alone. A CA who charges ₹2,000 for GST filing but misses reconciliations can create a ₹50,000 demand notice. The cheapest option is rarely the cheapest outcome.

Not checking ICAI registration. Unregistered tax practitioners exist. They can file returns but cannot sign audit reports, and they have no professional accountability.

Assuming one CA can do everything equally well. Transfer pricing and MSME GST compliance are completely different skill sets. The best CA firms in Gurgaon specialize. Choose one that specializes in what you actually need.

Not getting an engagement letter. Verbal commitments about scope and fees lead to disputes. A written engagement letter protects both sides.

Waiting until the deadline. Most CA problems in Gurgaon start because someone calls for help three days before the filing deadline. Good advisors can fix a lot — but not everything, and not always on a three-day notice.

Ignoring Haryana-specific compliance. Gurgaon businesses fall under GST state code 06 (Haryana), and the Gurugram CGST Commissionerate has its own audit patterns, dispute resolution history, and procedural expectations. A CA with Haryana-specific experience is meaningfully different from one who has only worked in Delhi or other states.

Why KKS Capital Advisors Stands Out Among CA Firms in Gurgaon

Most top car firms in Gurgaon focus purely on compliance. They are good at filing returns, completing audits, and managing regulatory paperwork. That is important. But it is not everything.

KKS Capital Advisors was built on a different premise — that growing businesses need financial strategy and compliance to work together, not as separate functions managed by separate people.

Here is what that looks like in practice. When a startup at KKS Capital Advisors is preparing for a fundraise, the same team that manages their GST and books also runs their business valuation and helps structure the transaction. There is no handoff. No miscommunication between the compliance CA and the finance advisor. No gaps in the story the numbers tell.

The firm’s service areas span tax advisory, GST, accounting and audit, corporate finance, business valuation, and business incubation — making it one of the genuinely full-service chartered accountant firms in Gurgaon for businesses that are building something, not just staying compliant.

For founders, promoters, and finance heads who want a single, accountable advisor across multiple financial functions, KKS Capital Advisors is worth a serious conversation.

FAQ'S

Q1. Which is the best CA firm in Gurgaon?

The best CA firm depends on your needs. For full-service support across tax, audit, and startup advisory, KKS Capital Advisors is a strong option among the top 10 CA firms in Gurgaon. Compare services before you decide.

Fees vary by service and complexity. Basic ITR filing can start low, while audits and advisory cost more. Always ask for a written quote and a clear scope of work before you sign up.

Most top CA firms in Gurgaon offer tax filing, GST, TDS, statutory audit, ROC compliance, bookkeeping, and advisory. Some also handle FEMA, transfer pricing, and startup valuation. Choose based on your priority.

Yes. Many firms, including KKS Capital Advisors, specialise in startup needs. They help with incorporation, ESOPs, valuation, funding support, and ongoing compliance, so founders can focus on building the business.

Check whether the chartered accountant is registered with ICAI. Ask for a membership number, review client feedback, and confirm the firm has experience in your industry before you engage them.

Read More

ITR-1 Sahaj Filing Guide for Salaried Employees AY 2026-27

ITR-1 Sahaj Filing Guide for Salaried Employees AY 2026-27

Introduction

Every year, millions of salaried Indians sit down before the tax deadline and ask the same question: ‘Which ITR form do I need to file?’ If you earn a salary, have one house property, and some interest income, the answer is almost always ITR 1 SAHAJ filing. This form is designed to keep things straightforward for individual taxpayers — and filing it correctly can save you time, penalties, and unnecessary notices from the Income Tax Department.

In this guide by KKS Capital Advisor, we cover everything you need to know about ITR 1 SAHAJ filing for Assessment Year 2026-27 (Financial Year 2025-26). From who qualifies to a step-by-step walkthrough of the online process — you’ll find it all right here.

What Is ITR 1 SAHAJ?

ITR 1 SAHAJ is the simplest income tax return form notified by the Income Tax Department of India. The word ‘SAHAJ’ means ‘easy’ in Hindi, and this form lives up to its name. It is meant for individual resident taxpayers whose total income does not exceed Rs 50 lakh and comes from specific, limited sources like salary, one house property, and interest income.

It is a single-page form (in its online version) and requires far fewer disclosures compared to ITR 2 or ITR 3. That’s what makes it the most popular ITR form in India — simple, quick, and easy to file online.

ITR 1 SAHAJ Eligibility: Who Can File?

Before you begin the ITR 1 filing process, you must confirm that you qualify to use this form. Not every salaried individual is eligible. Here’s who can file ITR 1 SAHAJ:

  •       Individual resident taxpayers only (not HUF, firms, or companies)
  •       Total income up to Rs 50 lakh during FY 2025-26
  •       Income from salary or pension
  •       Income from one house property (excluding cases of brought-forward losses)
  •       Income from other sources such as savings account interest, FD interest, family pension
  •       Agricultural income up to Rs 5,000

Who Cannot Use ITR 1 SAHAJ?

Just as important is knowing who should NOT file ITR 1. You must switch to a different form if:

  •       Your total income exceeds Rs 50 lakh
  •       You are a Non-Resident Indian (NRI) or Not Ordinarily Resident (NOR)
  •       You have income from capital gains (short-term or long-term)
  •       You have income from more than one house property
  •       You are a director in a company or hold unlisted equity shares
  •       You have foreign income or foreign assets
  •       You have brought-forward losses under any head of income
  •       You have income from business or profession
  •       You have deposited more than Rs 1 crore in current accounts, paid electricity bills exceeding Rs 1 lakh, or spent more than Rs 2 lakh on foreign travel (high-value transaction disclosures)

ITR 1 vs ITR 2 vs ITR 4: Quick Comparison

Confused about which form applies to you? This table should help:


Feature

ITR 1 (SAHAJ)

ITR 2

ITR 4 (SUGAM)

Who can use

Salaried individuals

Individuals with capital gains

Freelancers & small businesses

Income limit

Up to Rs 50 lakh

No limit

Up to Rs 50 lakh (business)

Salary income

Yes

Yes

Yes

Capital gains

No

Yes

No

Business income

No

No

Yes (presumptive)

Foreign income/assets

No

Yes

No

Multiple house properties

No

Yes

No

Complexity level

Simple

Medium

Medium

Documents You Need Before Filing ITR 1 Online

The ITR 1 SAHAJ filing online process is easier when you have all the documents ready beforehand. Here’s your checklist:

  •       Form 16 from your employer (Part A and Part B)
  •       Form 26AS and Annual Information Statement (AIS) from the IT portal
  •       PAN card and Aadhaar number
  •       Bank account details (account number and IFSC code)
  •       Interest certificates from banks for savings and FD accounts
  •       Rental income details (if applicable — one property only)
  •       Home loan interest certificate (if claiming deduction under Section 24)
  •       Proof of deductions claimed under Section 80C, 80D, 80G, etc.

How to File ITR 1 SAHAJ Online: Step-by-Step Process

Filing the ITR 1 SAHAJ form online is straightforward if you follow these steps carefully. Here’s how to do it:

  1.     Go to the official Income Tax e-filing portal: www.incometax.gov.in
  2.     Log in using your PAN/Aadhaar as user ID and your password. If you’re a first-time user, register your PAN first.
  3.     From the dashboard, click on ‘e-File’>’Income Tax Returns’>’File Income Tax Return’.
  4.     Select Assessment Year 2026-27, choose ‘Online’ mode, and click ‘Continue’.
  5.     Select ‘Individual’ as the status and choose ITR-1 SAHAJ as your form type. Confirm your choice.
  6.     The system will pre-fill available data from Form 26AS, AIS, and TIS. Review and validate each section carefully.
  7.     Fill in Part A: General Information — personal details, bank account, filing status (original/revised), and residential status.
  8.     Fill in Part B: Gross Total Income — enter salary income as per Form 16, house property income (net of interest), and income from other sources.
  9.     Fill in Part C: Deductions — add all eligible deductions under Chapter VI-A (80C, 80D, 80G, 80TTA, etc.).
  10. Review Part D: Tax Computation — check the auto-calculated tax liability against what you’ve already paid via TDS.
  11. If tax is payable, pay it using Challan 280 before proceeding.
  12. Preview your ITR, then submit it. After submission, e-verify your return within 30 days using Aadhaar OTP, net banking, or by sending a signed physical ITR-V to CPC Bengaluru.

New Tax Regime vs Old Tax Regime: Which Should You Choose?

From AY 2026-27, the new tax regime is the default regime. If you want to switch to the old regime (to claim deductions), you must actively opt for it while filing your return. Here’s what you need to know:

  •       New Tax Regime: Lower tax slabs, but most deductions and exemptions are not allowed
  •       Old Tax Regime: Higher tax slabs, but you can claim HRA, LTA, 80C, 80D, and other deductions
  •       For most salaried employees with home loans, insurance, and ELSS investments — the old regime may still offer more savings
  •       Use the tax calculator on the IT portal to compare both regimes before choosing

The ITR 1 form allows you to choose your preferred regime. Once you select it and submit, changing it after the deadline is very difficult — so pick carefully.

Key Deductions You Can Claim Under ITR 1 SAHAJ Filing

If you’ve chosen the old tax regime, make sure you don’t miss these deductions:

  •       Section 80C: Up to Rs 1.5 lakh (PPF, ELSS, EPF, life insurance premium, principal repayment of home loan, tuition fees)
  •       Section 80D: Health insurance premium — up to Rs 25,000 for self/family; Rs 50,000 for senior citizen parents
  •       Section 80TTA: Interest from savings account up to Rs 10,000
  •       Section 80TTB: For senior citizens, interest from deposits up to Rs 50,000
  •       Section 24(b): Home loan interest up to Rs 2 lakh for self-occupied property
  •       Section 80G: Donations to approved funds and charitable institutions
  •       Standard Deduction: Rs 75,000 for salaried taxpayers (increased in Budget 2024-25)

Common Mistakes to Avoid in ITR 1 SAHAJ Filing

Even small errors can get your return flagged or rejected. Here are the most common mistakes taxpayers make:

  •       Filing the wrong ITR form — always check eligibility first
  •       Not reconciling your income figures with Form 26AS and AIS before filing
  •       Forgetting to report interest income from savings accounts or FDs
  •       Claiming deductions without proper documentation or proof
  •       Not e-verifying the return within 30 days of filing — an unverified return is treated as not filed
  •       Selecting the wrong assessment year — for FY 2025-26 income, the AY is 2026-27
  •       Entering incorrect bank account details, which can delay your refund
  •       Ignoring mismatches between pre-filled data and actual income

Important Due Dates for ITR 1 Filing AY 2026-27

Category

Due Date

Individuals (non-audit cases)

31st July 2026

Belated return (with penalty)

31st December 2026

Revised return

31st December 2026

Updated return (ITR-U)

Within 2 years from the end of AY

Expert Tips for Smooth ITR 1 SAHAJ Filing

  •       Always download your Form 26AS and AIS at least a week before filing — it gives you time to raise disputes if there are mismatches
  •       Check your Annual Information Statement (AIS) carefully — it reflects high-value transactions reported by banks, mutual funds, and other institutions
  •       If you changed jobs during the year, collect Form 16 from each employer and combine the income figures correctly
  •       Do not claim deductions you are not eligible for — the IT Department’s AI-powered scrutiny system catches these
  •       File early to avoid the last-minute rush and potential server issues on the portal

•       Consult a tax advisor from KKS Capital Advisor if you have any doubts about your eligibility or deductions


FAQ'S

Q1. What is the income limit for ITR 1 SAHAJ filing?

The total income must not exceed Rs 50 lakh for the relevant financial year. This includes income from salary, one house property, and other sources like interest income. If your income crosses Rs 50 lakh, you need to file ITR 2 or another applicable form.

No. ITR 1 SAHAJ allows income from only one house property. If you earn rent from two or more properties, you must file ITR 2 instead. The eligibility condition is strict on this point.

Yes, but only up to Rs 5,000. If your agricultural income exceeds Rs 5,000, you cannot file ITR 1 and will need to use ITR 2.

No. ITR 1 is only for individual resident taxpayers. Non-Resident Indians (NRIs) and individuals with Not Ordinarily Resident (NOR) status must use ITR 2 for filing their income tax returns.

Your return will be treated as invalid and not filed if you don’t e-verify it within 30 days of submission. You must e-verify using Aadhaar OTP, net banking, DEMAT account, or by physically sending the signed ITR-V to CPC Bengaluru.

Yes, if you’re in the old tax regime and receive HRA as part of your salary, you can claim the exemption. Ensure your Form 16 reflects the HRA exemption correctly, or manually calculate and enter it in the salary details section.

If you file after 31st July 2026 but before 31st December 2026, you’ll face a late fee of Rs 5,000 under Section 234F. For taxpayers with income below Rs 5 lakh, the maximum late fee is Rs 1,000.

Yes. If you discover an error after submission, you can file a revised return before 31st December 2026 under Section 139(5). Make sure to select ‘Revised Return’ and enter the acknowledgement number from your original return.

Conclusion

ITR 1 SAHAJ filing is designed to make the tax filing process simple for salaried individuals and pensioners in India. But ‘simple’ doesn’t mean ‘careless’ — a small mistake can lead to notices, penalties, or loss of refunds. Understanding your ITR 1 SAHAJ eligibility, gathering the right documents, and following the step-by-step process make everything far smoother.

Whether you’re filing your first ITR or the tenth, the key is to be accurate, honest, and timely. The deadline for AY 2026-27 is 31st July 2026, and the earlier you file, the better.

At KKS Capital Advisor, we help individuals and families navigate the ITR 1 filing process with confidence. From checking your eligibility to e-verifying your return — our team makes tax filing stress-free.

Read More

ITR 4 Sugam Filing Guide 2026: Eligibility, Due Dates & Tax Rules

ITR 4 Sugam Filing Guide 2026: Eligibility, Due Dates & Tax Rules

Introduction

If you run a small business, work as a freelancer, or earn income as a professional — and you’ve been wondering how to file ITR 4 SUGAM — this guide is exactly what you need. ITR 4 SUGAM is the go-to form for small business owners and self-employed professionals who fall under the presumptive taxation scheme. It simplifies the entire process by removing the requirement for maintaining detailed books of accounts, which is a huge relief for lakhs of small taxpayers.

In this comprehensive guide by KKS Capital Advisor, we break down everything about ITR 4 SUGAM filing for AY 2026-27 (FY 2025-26) — from eligibility and the presumptive income scheme to a clear step-by-step filing walkthrough. Let’s get you ready to file accurately and on time.

What Is ITR 4 SUGAM?

ITR 4 SUGAM is the income tax return form for individuals, Hindu Undivided Families (HUFs), and firms (other than LLPs) who opt for the presumptive taxation scheme under Sections 44AD, 44ADA, or 44AE of the Income Tax Act. The word ‘SUGAM’ means ‘convenient’ in Hindi — and for eligible taxpayers, this form truly delivers on that promise.

Instead of calculating actual profits, presumptive taxation lets you declare a fixed percentage of your turnover as income. This removes the burden of maintaining complex accounting records, making the ITR 4 form AY 2026-27 ideal for small businesses and working professionals with relatively simple finances.

ITR 4 SUGAM Eligibility: Who Can File?

Before you start the ITR 4 SUGAM filing process, check if you qualify. Here’s who is eligible:

  •       Individual taxpayers, HUFs, and partnership firms (excluding LLPs)
  •       Resident taxpayers only — NRIs cannot use this form
  •       Total income up to Rs 50 lakh
  •       Business income under Section 44AD (turnover up to Rs 3 crore for non-cash businesses or Rs 2 crore otherwise)
  •       Professional income under Section 44ADA (gross receipts up to Rs 75 lakh for non-cash transactions; Rs 50 lakh otherwise)
  •       Income from goods carriage under Section 44AE (owning not more than 10 goods vehicles)
  •       Salary/pension income
  •       Income from one house property
  •       Income from other sources like interest

Who Cannot File ITR 4?

You should not use the ITR 4 SUGAM form if:

  •       You are a company, LLP, or Association of Persons (AOP)
  •       Your total income exceeds Rs 50 lakh
  •       You have capital gains income
  •       You have income from more than one house property
  •       You have foreign income or foreign assets
  •       You hold unlisted equity shares or are a director in a company
  •       You want to opt out of presumptive taxation and maintain regular books of accounts

Presumptive Taxation Under ITR 4: Sections 44AD, 44ADA & 44AE Explained

The heart of the ITR 4 SUGAM filing is the presumptive taxation scheme. Understanding each section will help you declare income correctly.


Section

Who It Applies To

Turnover / Receipt Limit

Deemed Income %

44AD

Small businesses (trading, manufacturing, etc.)

Up to Rs 3 Cr (non-cash) / Rs 2 Cr (otherwise)

8% of turnover (6% for non-cash transactions)

44ADA

Specified professionals (doctors, CAs, architects, lawyers, etc.)

Up to Rs 75 lakh (non-cash) / Rs 50 lakh

50% of gross receipts

44AE

Transporters owning goods vehicles

Max 10 goods vehicles

Rs 1,000 per ton per month (heavy vehicles); Rs 7,500/month (others)

Important Note on Section 44AD

If you opt for Section 44AD in any assessment year, you must continue using it for the next 5 consecutive years. If you opt out during this period, you won’t be able to use Section 44AD for the next 5 years. This is a critical decision — plan before you file.

Documents Required for ITR 4 SUGAM Filing

Keep these documents ready before you begin the ITR 4 form AY 2026-27 filing:

  •       PAN card and Aadhaar number
  •       Bank account details (all accounts used for business)
  •       Form 26AS and Annual Information Statement (AIS)
  •       Form 16A or TDS certificates from clients
  •       Details of total turnover or gross receipts for FY 2025-26
  •       Advance tax payment challans (if any)
  •       Proof of deductions to be claimed under Chapter VI-A (80C, 80D, etc.)
  •       Rental income details if you have one house property
  •       Interest income statements from banks

How to File ITR 4 SUGAM Online: Step-by-Step Process

Here’s your complete step-by-step guide to ITR 4 SUGAM filing online for AY 2026-27:

  1.     Visit the Income Tax e-filing portal at www.incometax.gov.in. Log in using your PAN or Aadhaar as your user ID along with your password.
  2.     From the dashboard, navigate to ‘e-File’>’Income Tax Returns’>’File Income Tax Return’.
  3.     Select Assessment Year 2026-27, choose ‘Online’ mode, and click ‘Continue’.
  4.     Under the filing status question, select ‘Individual’, ‘HUF’, or ‘Firm’ — whichever applies to you. Then choose ITR-4 as your form.
  5.     The portal will pre-fill data from Form 26AS, AIS, and your employer records. Review all pre-filled information carefully for accuracy.
  6.     Go to Part A: General Information — enter your personal details, business/profession details, and bank account information.
  7.     Fill in Part B: Income Details — Enter your turnover or gross receipts and select the applicable section (44AD, 44ADA, or 44AE). The portal will compute presumptive income automatically.
  8.     Add salary income (if any), house property income, and other source income in the relevant sections.
  9.     Fill in Part C: Deductions — Enter all deductions under Chapter VI-A that you are eligible for.
  10. Review Part D: Tax Computation — cross-check the tax calculated against your TDS and advance tax payments. Pay any remaining tax via Challan 280 before submission.
  11. Preview the complete ITR 4 form and submit it once you are satisfied with the entries.
  12. E-verify your return within 30 days using Aadhaar OTP, net banking, or by posting the physical ITR-V to CPC Bengaluru.

New Tax Regime vs Old Tax Regime for ITR 4 Filers

ITR 4 filers can also choose between the new and old tax regimes. Here’s what you need to know for AY 2026-27:

  •       New Tax Regime: Default from AY 2024-25. Lower tax rates but no deductions for 80C, 80D, HRA, etc. For business income, Section 44AD presumptive income still applies.
  •       Old Tax Regime: You can claim deductions like 80C (up to Rs 1.5 lakh), 80D (health insurance), 80G (donations), home loan interest, etc. This can significantly reduce tax for those with heavy investments.
  •       Businesses under Section 44AD must file Form 10-IEA to opt for the old tax regime. Missing this step means you’ll be taxed under the new regime by default.

Use the tax calculator available on the IT portal to run both scenarios before deciding. The right choice depends entirely on your actual expense and investment patterns.

Expert Tips for ITR 4 SUGAM Filing — Best Practices

  •       Match your declared turnover with GST returns (GSTR-1, GSTR-3B) to avoid discrepancies — the tax department cross-checks these
  •       Keep a basic record of receipts and payments even under presumptive taxation — it helps if your return is picked up for scrutiny
  •       If your actual profit is higher than 8% or 50% under presumptive tax, declare the actual figure to avoid future queries
  •       File advance tax on time (by 15th March each year) to avoid interest under Sections 234B and 234C
  •       Don’t forget to report all bank accounts in the return, even those not actively used for business
  •       If you crossed the turnover threshold during FY 2025-26, switch to ITR 3 and maintain proper books of accounts
  •       Reach out to KKS Capital Advisor for help evaluating which section (44AD vs 44ADA vs 44AE) applies to your specific income type

Common Mistakes to Avoid When Filing ITR 4 SUGAM

  •       Filing ITR 4 despite having capital gains — you must use ITR 3 in such cases
  •       Declaring income below the presumptive limit (8% or 50%) without opting out properly — this attracts scrutiny
  •       Not matching turnover with GST returns — a major red flag for the IT Department
  •       Forgetting to report interest income from savings accounts or FDs
  •       Missing the e-verification step — an unverified return is treated as not filed
  •       Not paying advance tax when total tax liability exceeds Rs 10,000 — leads to interest charges
  •       Using ITR 4 if your LLP earnings are your primary business income — LLPs must use ITR 5

Due Dates for ITR 4 SUGAM Filing AY 2026-27

Taxpayer Category

Due Date

Individuals, HUFs, Firms (non-audit cases)

31st July 2026

Businesses requiring tax audit (turnover > Rs 1 crore)

31st October 2026

Belated return (with late fee)

31st December 2026

Revised return

31st December 2026

Updated return (ITR-U)

Within 2 years from end of AY

FAQ'S

Q1. Who is required to file ITR 4 SUGAM?

ITR 4 SUGAM is filed by individuals, HUFs, and firms (not LLPs) who opt for the presumptive taxation scheme under Sections 44AD, 44ADA, or 44AE, with total income up to Rs 50 lakh. It’s ideal for small business owners, freelancers, and specified professionals.

For FY 2025-26, the turnover limit under Section 44AD is Rs 2 crore for businesses where cash transactions exceed 5% of total receipts, and Rs 3 crore for businesses where cash transactions are 5% or less. The higher limit encourages digital payments.

Yes. Doctors, chartered accountants, architects, lawyers, engineers, and certain other specified professionals can file ITR 4 under Section 44ADA, provided their gross receipts don’t exceed Rs 75 lakh (for non-cash) or Rs 50 lakh (otherwise). They declare 50% of gross receipts as income.

Yes. Even under presumptive taxation, you can claim deductions under Section 80C, 80D, 80G, and other applicable sections. These reduce your taxable income after the presumptive income is calculated. Make sure you’re in the old tax regime to avail these deductions.

If your actual profit is lower than the presumptive rate (8% or 50%), you can declare your actual lower profit. However, in that case, you must maintain books of accounts as per Section 44AA and get a tax audit done if your income exceeds the basic exemption limit.

Not always. GST turnover includes the value of supply, while income tax turnover may differ based on nature of income and adjustments. Always reconcile both carefully. Discrepancies between GSTR returns and ITR 4 declarations can invite notices from tax authorities.

No. Section 44AE is available only if you own 10 or fewer goods vehicles at any time during the financial year. If you exceed this limit, you cannot use the presumptive scheme under this section and must maintain regular books and file ITR 3.

You can e-verify through Aadhaar OTP, net banking login, DEMAT account, or by generating an Electronic Verification Code (EVC). E-verification must be done within 30 days of submission. Without e-verification, your return is treated as invalid.

Conclusion

Understanding how to file ITR 4 SUGAM correctly can save you considerable time and effort as a small business owner or freelancer. The presumptive taxation scheme is one of the most taxpayer-friendly provisions in India’s income tax law—it reduces paperwork and makes compliance achievable even without an accountant.

But you still need to verify your eligibility, report income accurately, match your turnover with GST records, and file on time. Getting even one part wrong can lead to notices, penalties, or the dreaded tax scrutiny.

At KKS Capital Advisor, we specialize in ITR 4 SUGAM filing for small businesses, freelancers, doctors, architects, and professionals across India. Our team ensures your return is accurate, compliant, and filed well before the deadline for AY 2026-27.


Read More

How to Save Tax for Salary Above 12 Lakhs: Smart Planning for Salaried Employees

How to Save Tax for Salary Above 12 Lakhs: Smart Planning for Salaried Employees

If your annual salary is above 12 lakhs, you are likely in a higher tax bracket. Knowing how to save tax for salary above 12 lakhs is crucial to keep more of your hard‑earned money instead of paying more in income tax. With the right tax‑saving tools and smart planning, you can reduce your taxable income, lower your tax liability, and even grow your savings at the same time.

This article explains the best, practical ways to save tax for a 12‑lakh salary and beyond, using simple language and clear steps you can follow.

Why tax savings matter for 12‑lakh salary

When your salary is above 12 lakhs, income tax can feel heavy. At this income level, effective tax planning is no longer optional—it becomes a necessity.

Smart tax saving helps you:

  • Reduce your taxable income under Section 80C, 80D, and other deductions.
  • Lower your effective tax rate instead of paying more to the department.
  • Build long‑term wealth through eligible investments like PPF, ELSS, NPS, and more.
  • Avoid last‑minute rush and missed opportunities in the financial year.

Understanding tax calculation for 12 lakh salary will also help you plan better and choose the best tax‑saving options for salaried employees.

Know your tax bracket first

Before you plan how to save tax for salary above 12 lakhs, check which tax slab you fall into under the new tax regime (most salaried people use this now).

Here is a quick overview of tax slabs (approximate, subject to the latest budget changes):

           Income Range (₹)

             Tax Rate

                0 – 3,00,000

                Nil

               3,00,001 – 6,00,000

                5%

                6,00,001 – 9,00,000

                10%

              9,00,001 – 12,00,000

                15%

                 12,00,001 – 15,00,000

               20%

              Above 15,00,000

                30%

A 12‑lakh salary is usually in the 15–20% effective tax band, depending on cess, surcharge, and deductions. If you can reduce taxable income close to or below 12 lakhs, you can often save several thousand rupees in tax every year.

Best tax saving options for salaried employees

tax-saving options for salaried employees

To know how to save tax for salary above 12 lakhs, start with the most popular and safe options under the Income Tax Act.

1. Use Section 80C deductions (up to ₹1.5 lakh)

Section 80C offers many ways to reduce taxable income. You can invest up to ₹1.5 lakh here.

Best options for salaried employees:

  • EPF (Employee Provident Fund): Your monthly PF contribution is automatically eligible for 80C.
  • PPF (Public Provident Fund): Safe, long‑term saving with interest and tax‑free maturity.
  • ELSS (Equity Linked Savings Scheme): Tax‑saving mutual funds with 3‑year lock‑in but higher return potential.
  • Life Insurance premiums on eligible plans (your own or spouse/children).
  • Children’s tuition fees for up to 2 children.
  • 5‑year tax‑saving fixed deposits with banks.

2. Save tax through Section 80D (Health insurance)

You can claim up to ₹25,000–₹75,000 under Section 80D, depending on age and dependents.

  • Up to ₹25,000 for self, spouse, and children.
  • Extra ₹25,000 for parents (if below 60).
  • Extra ₹50,000 for senior citizen parents (60+).

This not only helps reduce tax liability but also builds health cover for your family.

3. HRA and rent for tax saving

If you are not living in your own house, you can claim House Rent Allowance (HRA) and also file rent receipts with your employer.

Key points:

  • HRA is exempt from tax up to a certain limit (least of: actual HRA, 50% of basic for metro / 40% for non‑metro, or actual rent minus 10% of basic).
  • If you live in a rented house, keep the rent receipts and PAN of the landlord (if rent > ₹50,000 per month).
  • You can also claim home loan interest under Section 24 (up to ₹2 lakh per year) if you own a house.

4. NPS – Extra tax saving option

The National Pension System (NPS) under Section 80CCD(1B) allows an extra deduction of ₹50,000 beyond the usual 80C limit.

  • Pushes your total tax saving above ₹1.5 lakh.
  • Builds a retirement corpus with government‑backed security.
  • Good option if you want long‑term tax saving for 12 lakhs salary and higher.

Step-by-step guide: How to save tax for salary above 12 lakhs

Follow this simple plan to design your tax strategy:

Step 1: Check your Form 16 and salary breakup

  • Note your basic salary, HRA, special allowance, and other components.
  • See what deductions your employer already uses (PF, 80C investments reported, etc.).

Step 2: Plan your 80C investments

  • Decide how to split your ₹1.5 lakh 80C limit between:
    • EPF (through your salary).
    • PPF (₹50,000–75,000 per year).
    • ELSS (₹25,000–50,000 per year).

Step 3: Buy or review health insurance

  • Ensure at least one family health insurance policy.
  • Add top‑up or critical illness cover if needed.
  • Claim Section 80D with proper bills and policy details.

Step 4: Claim HRA and rent

  • If you pay rent, submit rent receipts and landlord details to your HR.
  • If you own a house, plan for home loan interest and property tax deductions.

Step 5: Use NPS for extra savings

  • Open an NPS account (Tier‑I) and invest ₹50,000 per year.
  • Claim an extra ₹50,000 deduction under 80CCD (1B).

Step 6: Save interest from savings accounts

  • Use Section 80TTA/80TTB to claim up to ₹10,000 in interest deductions from savings accounts (if applicable).

Step 7: Declare all eligible deductions

  • Submit proofs to your company on time.
  • If you missed some, file ITR and claim missing deductions.

Common mistakes when saving tax on a 12‑lakh salary

Here are frequent errors people make:

  • Delaying investments till March: Many wait till the last month, then buy unsuitable or low‑return options.
  • Ignoring NPS and HRA: Missing out on extra ₹50,000 under NPS and HRA exemptions can cost you tax savings.
  • Not updating declarations: New job, new rent, or new insurance? Not updating your employer cuts your real tax savings.
  • Mixing tax saving with returns: Some buy expensive insurance or unknown schemes just for tax saving. Focus on safe lock-in, and returns, RNS too.

ALSO READ: TDS Section 194S of Income Tax Act

Tips and best practices for maximum savings

To really know how to save tax for a salary above 12 lakhs, keep these tips in mind:

  • Plan early in the year: Start May–June, not March.
  • Spread investments: Use PPF for safety, ELSS for growth, and NPS for extra deduction.
  • Talk to a tax advisor: Experts such as KKS Capital Advisor can help you choose the right mix of tax savings for a 12 lakh salary and retirement planning.
  • Review every year: Your salary, family, and liabilities change; your tax plan should also change.
  • Use online tools: Many tax calculators help you see the tax calculation for a 12 lakh salary and how much you can save with each option.

Conclusion: Take smart action this year

Understanding how to save tax for a salary above 12 lakhs can make a big difference in how much you keep every year. By using Section 80C, 80D, HRA, NPS, and other legal deductions, you can lower your tax, build a safety net, and grow your wealth.

If you are not sure about the best mix for your income and goals, consult a qualified tax advisor or financial planner like KKS Capital Advisor and get a customized plan.

Got a 12‑lakh salary and higher? Start planning your tax‑saving investments this month instead of next March. Use this guide to create your own tax-saving checklist for salaried employees and keep more of your income legally and safely.

FAQ'S

How much tax will I pay on a 12‑lakh salary?

For a 12‑lakh salary, your effective tax rate is usually around 15–20% after deductions. The exact amount depends on your deductions under 80C, 80D, HRA, and other sections plus cess.

The top options are EPF, PPF, ELSS, NPS, health insurance under 80D, and HRA/rent deductions. A mix of safety and growth‑oriented tools works best.

Yes. Even if you live in your own house, you can claim home loan interest deduction under Section 24 and, if you have health insurance, Section 80D. NPS and 80C investments are also available.

Yes. NPS under Section 80CCD(1B) gives an extra ₹50,000 deduction beyond the 1.5‑lakh 80C limit. It is especially useful for salaried employees earning above 12 lakhs who want higher deductions and a retirement fund.

Yes. A tax advisor or financial planner can give you a clear view of your tax calculation for 12 lakh salary and suggest the best tax‑saving mix based on your expenses, family, and goals.

Read More